Buying before you sell is the part of moving that keeps Colorado homeowners up at night. You find the right place in Evergreen, Conifer or Golden, but your current home isn't sold yet. Or it sold, and now you have nowhere to land. Either way, one half of the move is holding the other half hostage.
One of the lenders we work with, Movement Mortgage, offers a Buy Before You Sell program, called BBYS, built for exactly this problem. Here is how it works, who it may fit, and the questions to ask before you decide.
Why Timing a Move Is So Hard
Most people handle a move in one of three ways. They make an offer contingent on selling their home. They sell first and rent or stay with family while they hunt. Or they carry two mortgages for a while and hope the math holds.
Each one has a cost. A contingent offer can lose to a cleaner offer. Selling first means moving twice, and nobody wants to move twice, especially with a piano. Carrying two mortgages works until it doesn't.
It gets harder in the foothills. Homes in Evergreen, Conifer, Pine and Morrison often sit on acreage, have unique layouts, and don't come up every week. When the right one appears, you may not have months to wait on your sale.
What Is the Buy Before You Sell Program?
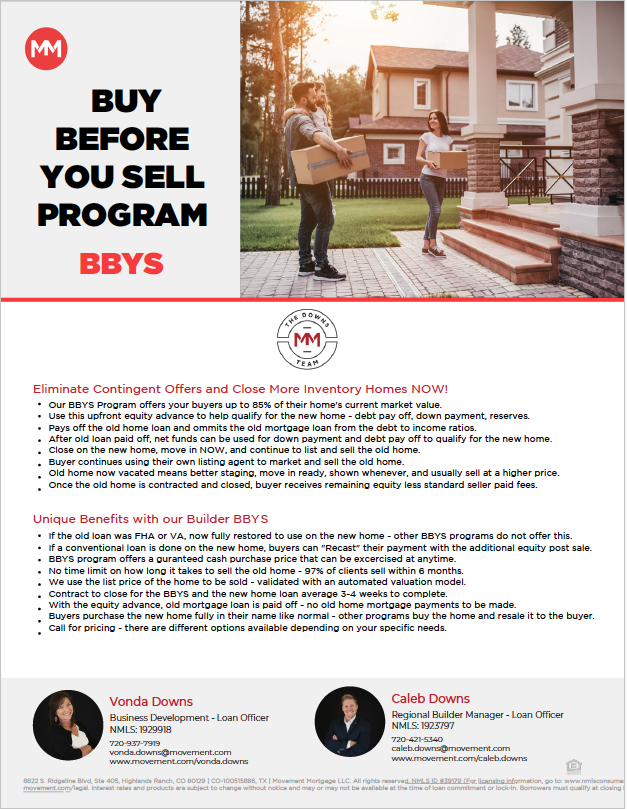
The BBYS program lets you tap the equity in your current home before it sells. Movement describes it as an upfront equity advance of up to 85% of your home's current market value. That advance is used to pay off your old mortgage, which also takes that loan out of your debt to income ratio.
In plain terms, the old house stops counting against you when you apply for the new loan. That can make qualifying for the next home much easier.
How It Works, Step by Step
1. You use your equity up front
The advance can pay off your old home loan. After that, the net funds can go toward a down payment, paying off other debt, or building reserves for the new purchase.
2. You close on the new home and move in
You are no longer waiting on a buyer to make your move work. You settle into the new place first, on your own timeline.
3. You list and sell the old home with your own agent
You keep your own listing agent to market and sell the old house. A vacant home is easier to stage and easier to show at a moment's notice. Movement says vacated homes usually sell for more. That isn't guaranteed, but an empty house photographs better and never has a dog hair problem on showing day.
4. You collect what's left after the sale
When the old home is under contract and closes, you receive the remaining equity, less standard seller paid fees.
Who Might This Fit?
The program tends to make sense when you have meaningful equity and a move you want to make on your terms. A few situations we see around Jefferson County and the foothills:
- Homeowners moving up to a bigger property in Evergreen, Conifer or Pine
- Longtime owners in Golden, Lakewood or Arvada who want to right size without a rushed sale
- Buyers who don't want to make a contingent offer on a competitive listing
- Families who want one move instead of two
Whether it fits you depends on your equity, your credit, and the loan on the new home. Qualification is set by Movement, not by us.
Questions to Ask Before You Use It
Any tool that uses your equity deserves a few hard questions. Ask them up front:
- What does it cost, and what options are available for my situation?
- How will my home's value be determined?
- What happens if my home takes longer to sell than I expect?
- How does the advance affect the loan I need on the new home?
- What fees come out when the old home closes?
Pricing is not one size fits all. Movement says to call for pricing, since there are different options depending on your needs. A good conversation with a loan officer should answer every question on that list.
How Does This Compare to Other Ways to Buy First?
There is more than one way to buy before you sell. A home equity line of credit lets you borrow against your current home, but it adds a payment and can complicate qualifying. A bridge loan is short term financing with its own costs. A contingent offer costs nothing up front but can weaken your position with sellers. Selling first and renting is simple but means two moves.
None of these is right for everyone. The point is to compare them with real numbers before you fall in love with a house.
Why Your Listing Strategy Still Matters
Even with this program, the old house still has to sell. Smart pricing and strong marketing decide how long that takes and what you net. If you plan to use BBYS, talk to a listing agent before you buy, not after. We'd be glad to be that agent, and we'll give you honest numbers on what your home is likely to bring.
Quick Answers
Can I buy a house in Colorado before selling mine?
Yes. Common routes include a contingent offer, a home equity line, a bridge loan, or a program like BBYS. The right one depends on your equity, your timeline and your finances.
Does BBYS pay off my old mortgage?
According to Movement, yes. The equity advance pays off the old loan, and that loan is removed from your debt to income ratio when you qualify for the new home.
Do I have to use Movement Mortgage?
No. You are free to use any lender. We share this program because it is worth knowing about.
See the One Page Overview
Movement put together a one page summary of the program. Download the BBYS overview here.
Thinking About a Move? Let's Talk.
Even a maybe someday move is worth a 10 minute conversation. We'll talk through your timeline, what your home might sell for, and whether this program is worth a closer look. If it is, we'll connect you with Vonda Downs at Movement Mortgage.
Email: Tim@JonesTeamColorado.com
Call or text: (720) 314-8462
Book a quick call: https://calendly.com/tim-jonesteam/15min
Tim and Sandy Jones
Jones Team Colorado | eXp Realty
Program terms, availability and qualification are set by Movement Mortgage LLC, NMLS ID #39179. Vonda Downs, Loan Officer, NMLS #1929918. This is not a commitment to lend. Interest rates and products are subject to change without notice and may not be available at the time of loan commitment or lock-in. Borrowers must qualify at closing. You are free to use any lender. Jones Team Colorado is not a mortgage lender.